Salary Increases vs. Rising Expenses: How to Make a Pay Raise Actually Improve Your Finances

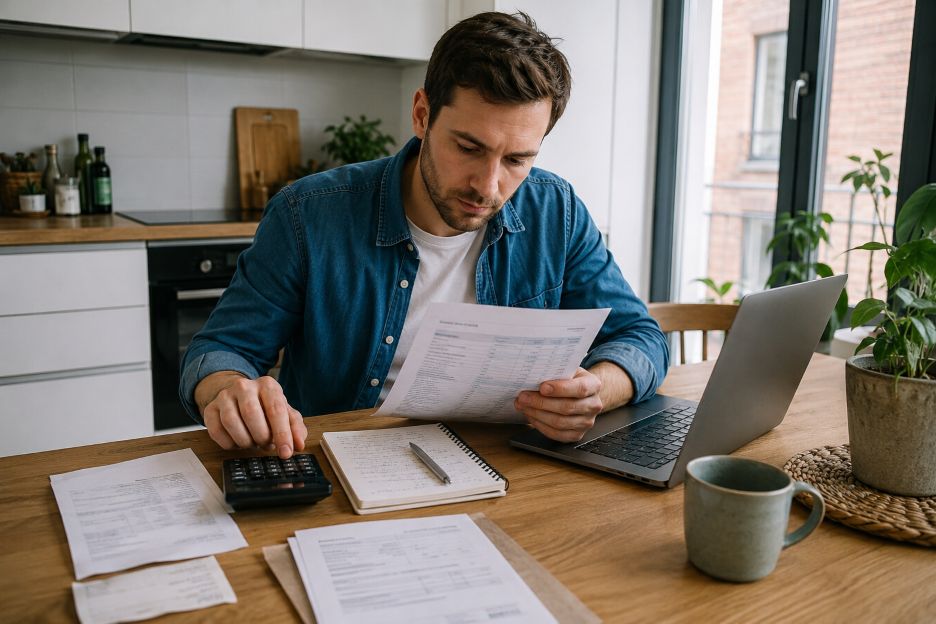
Focused Home Finances at the Kitchen Table

Consumer prices in Germany were 2.8% higher in July 2026 than a year earlier, with energy prices rising particularly strongly, data from Destatis, the German Federal Statistical Office, shows. That matters when workers receive a salary increase. A larger paycheck may look like an immediate improvement, but rising housing, transport, energy, insurance, and everyday costs can absorb part of the gain before it produces meaningful financial progress.

For employees covered by collective agreements, understanding exactly how much pay will change is a useful starting point. Workers may consult a public sector collective agreement table (tabelle tarifvertrag öffentlicher dienst) to compare salary levels and estimate how an adjustment could affect their income. The Federal Office for Central Services and Unresolved Property Issues confirms that the TVöD applies to employees working for the federal government and employers belonging to member associations of the municipal employers’ organization. Once the expected increase is clear, the more important question becomes what to do with the additional money.

First, Find Out How Much of the Raise Is Really Available

A percentage increase in gross salary is not the same as an identical increase in money available for spending. Before making new commitments, employees can compare their previous take-home pay with their first full paycheck after the increase.

The next step is reviewing current expenses. The Consumer Financial Protection Bureau recommends examining several months of spending when creating a realistic budget because irregular costs, such as insurance, repairs, medical expenses, gifts, and seasonal purchases, can easily be missed when looking at only one month.

This comparison helps separate a genuine improvement in disposable income from money that is already needed to cover higher living costs. If take-home pay rises by €120 per month but essential expenses have increased by €50, for example, treating the entire €120 as new spending money could quickly create pressure elsewhere in the budget.

Why Automatically Spending the Raise Can Limit Its Value

A salary increase often creates room for lifestyle improvements. A household might upgrade a phone plan, eat out more frequently, finance a newer vehicle, or add subscriptions. Some additional spending may be reasonable, especially when workers have postponed necessary purchases while prices were rising.

The problem appears when new recurring expenses consume the entire increase. Once additional monthly commitments become normal, the household may end up with roughly the same financial flexibility it had before the raise.

Current inflation makes this distinction particularly important. Destatis reported that German service prices increased 2.9% year over year in July 2026, while vehicle maintenance and repair costs rose 4.7%. Workers therefore need to consider their own spending patterns rather than assuming a negotiated wage increase translates directly into the same improvement in purchasing power.

Give the Extra Income a Job Before Spending It

One practical approach is deciding how the additional take-home pay will be divided before it reaches everyday spending. The exact percentages depend on individual circumstances, but the raise can be distributed among several priorities:

  • building or strengthening emergency savings;
  • paying down expensive debt;
  • saving for planned purchases;
  • investing for longer-term goals; and
  • allowing a reasonable amount for improved day-to-day living.

This approach does not require workers to save every additional euro. Instead, it prevents the entire increase from disappearing into unplanned consumption.

Emergency Savings Can Turn a Raise Into Financial Security

For someone without a financial cushion, emergency savings may deserve early attention. Research from the Consumer Financial Protection Bureau found substantial differences in financial well-being, debt profiles, and ability to meet obligations among consumers with different levels of emergency savings.

An emergency fund is designed for costs outside the normal monthly budget, such as urgent repairs or an unexpected loss of income. The Consumer Financial Protection Bureau also notes that even relatively small savings can provide some financial security and recommends automatic recurring transfers as one way to build a consistent savings habit.

A wage increase creates a convenient opportunity to automate this process. If someone was managing expenses on the previous salary, transferring part of the increase to savings immediately after payday may be easier than trying to find spare money at the end of each month.

Could Paying Debt Produce a Bigger Benefit?

Workers carrying costly consumer debt may decide that reducing balances provides more immediate value than increasing discretionary spending. For households dealing with several loans or repayment dates, understanding options for managing multiple debts can also help put different repayment strategies into perspective. Interest and fees can make an unexpected expense considerably more expensive when it has to be financed through borrowing, the Consumer Financial Protection Bureau warns.

A pay increase can therefore be used to raise monthly repayments without cutting the household’s previous standard of living. As balances fall, money that once went toward repayments can eventually be redirected toward savings, investing, or other goals.

Turn Temporary Breathing Room Into Long-Term Progress

Once immediate financial weaknesses are under better control, part of a salary increase can support longer-term objectives. These might include retirement, education, a future home purchase, or another major financial goal. The key is connecting additional income to a specific purpose instead of simply allowing spending to expand.

Financial improvement does not have to mean avoiding every lifestyle upgrade. A raise is still an opportunity to enjoy some additional flexibility. The more sustainable approach is to decide deliberately how much should improve life today and how much should strengthen tomorrow.

A Higher Salary Works Best With a Plan

Collectively negotiated wage increases can provide meaningful relief, particularly when households have been dealing with higher prices. Yet the size of the raise alone does not determine whether someone’s finances become stronger.

Workers who compare their new take-home pay with current expenses, build savings, reduce costly debt, and direct part of the increase toward future goals can make the adjustment work harder for them. Over time, the most valuable result of a pay increase may be less about what it allows someone to buy immediately and more about the financial choices it makes possible.
The Impact of Interest Rate Hikes on Savings and Loans

Loan Agreement

A New Move by the Federal Reserve

The Federal Reserve’s recent decision to increase interest rates by 0.25% has sent ripples across financial markets. This news is a welcome relief for savers as banks are likely to offer higher interest rates on deposits. For borrowers, however, it’s a different story. Mortgage rates, personal loans, and credit card APRs will climb, adding financial strain to households.

Why Savers Have a Reason to Rejoice

This shift underlines the importance of re-evaluating financial plans. If you’re saving, now’s the time to explore high-yield savings accounts or certificates of deposit (CDs) that could maximize your returns.

Borrowers Face New Challenges

For borrowers, prioritizing debt repayment is crucial. Consider consolidating loans to lock in lower rates and reduce long-term financial strain.

Small Businesses Brace for Higher Costs

Small businesses will also feel the heat. As borrowing costs rise, entrepreneurs may need to rethink expansion plans.

A Call for Proactive Financial Management

The rate hike serves as a reminder to stay proactive in managing finances, whether for personal savings or business funding.

The SMSF Property Investment Guide: Maximizing Your Financial Future

smsf property

Self-managed super funds (SMSFs) have become increasingly popular among individuals who want more control over their retirement savings. One of the key strategies for diversifying your SMSF portfolio is through property investment. In this article, we’ll explore the ins and outs of SMSF property investment, discussing the benefits, risks, and strategies to help you secure your financial future.

Understanding SMSF Property Investment

SMSF property investment refers to the process of using your self-managed super fund to purchase and hold property assets. It allows you to invest in real estate, which can potentially offer substantial long-term financial benefits. Here are some key points to consider when it comes to SMSF property investment:

  • Diversification: SMSFs often hold a mix of assets such as stocks, bonds, and cash. Including property in your portfolio can help spread the risk, reducing your exposure to fluctuations in any single asset class.
  • Tax Benefits: SMSFs offer certain tax advantages, particularly in terms of capital gains and rental income. Properly structured SMSF property investments can help you minimize tax liability and maximize returns.
  • Long-Term Growth: Historically, property values tend to appreciate over time, making it a viable option for building wealth and securing your retirement.

Benefits of SMSF Property Investment

SMSF property investment offers several advantages for investors looking to strengthen their retirement savings:

  • Control: With an SMSF, you have control over property investment decisions, including property selection, location, and financing options.
  • Portfolio Diversification: As mentioned earlier, diversifying your SMSF with property assets can help mitigate risks and provide a balanced portfolio.
  • Wealth Accumulation: Property investments often appreciate in value over time, allowing your SMSF to accumulate wealth for your retirement years.
  • Rental Income: Rental income generated from your property can be a valuable source of revenue within your SMSF, contributing to your financial well-being.

Risks Associated with SMSF Property Investment

While SMSF property investment offers many benefits, it’s essential to be aware of potential risks:

  • Liquidity: Property is a relatively illiquid asset, meaning it can be challenging to sell quickly if you need to access your funds in a hurry.
  • Maintenance and Costs: Property ownership comes with ongoing maintenance and costs, which can impact your SMSF’s overall returns.
  • Market Fluctuations: Property values can fluctuate, and economic conditions can affect the rental market. It’s crucial to be prepared for these fluctuations.
  • Regulatory Compliance: SMSFs are subject to strict regulatory requirements, and failing to comply with these rules can result in penalties. Seek professional advice to ensure you’re in compliance.

Strategies for SMSF Property Investment

To make the most of your SMSF property investment, consider these strategies:

  • Engage Expert Advice: It’s prudent to enlist the expertise of a financial consultant or an SMSF professional to assist you in navigating the intricacies of SMSF property investment.
  • Research and Due Diligence: Conduct thorough research on the property market, location, and potential rental income. Make informed decisions based on data and analysis.
  • Diversify Your Property Holdings: Avoid putting all your SMSF funds into a single property. Diversify across different properties to spread risk.
  • Regularly Review Your Portfolio: Periodically assess the performance of your property investments within your SMSF. Make necessary adjustments to optimize returns.
  • Plan for Retirement: Ensure that your SMSF property investments align with your retirement goals and objectives. Create a strategy that complements your overall retirement plan.

READ ALSO: Understanding The Significance Of Personal Finance

Conclusion

In conclusion, SMSF property investment can be a valuable addition to your self-managed super fund, offering diversification, tax benefits, and potential long-term growth. However, it’s crucial to understand the risks and implement effective strategies to make the most of this investment avenue. By seeking professional guidance and staying informed, you can work towards maximizing your financial future through SMSF property investment.

Finances Impact Gold Businesses

Financial management is a crucial part of any business. There are many ways that finances can impact a company’s success or failure. With so many options available, it’s hard to know which one is right for you and your business. However, an understanding of finances enables you to make better decisions that will help your business succeed.

In order to have a successful business like Goldcore, a trusted platform that buys and sells gold bullion, it is important for you to understand the financial aspects of your business. This company understands the importance of financial planning. This is why they can help people protect and grow their wealth.

What are the financial implications of starting a new gold and silver business?

The financial implications of starting a new business are significant, but the rewards can be great as well. But before you start your precious metal company, it is important to know what you’re getting yourself into.

It is important to know how much it will cost to start a business and how much profit you should expect in the first year. This way you can make sure that your venture is worth it and doesn’t put too much strain on your personal finances.

The importance of having a solid financial plan

The importance of having a solid financial plan is not to be taken too lightly. It is important to have a plan in place and make sure that you are prepared for the future. Financial plans can help you develop your potential and work towards achieving your goals. It’s important to know that there are certain things that can be done now so that when the time comes, you won’t have any regrets about not doing it earlier.

A financial plan is an essential part of your personal development process because it helps you understand how you can achieve your goals in the future. The process also helps you avoid negative consequences.

Goldcore

Why sales is more important than profit in businesses?

In the past few decades, businesses have been focusing more on profit than sales. However, this is not a sustainable business model.

Sales is more important than profit in business because it’s what keeps the company running. If a company makes a lot of money but doesn’t sell anything, then they are just wasting resources.

Companies that focus on sales have to have a strong customer service team that can provide customers with the best possible experience and make them feel valued. This will help them keep their customers and grow their revenue by making repeat purchases or referrals to friends and family members who may be interested in buying products from the company.